To file a personal injury claim in Florida, you must seek initial medical treatment within 14 days under Personal Injury Protection rules (Fla. Stat. § 627.736) and file your lawsuit within 2 years of the accident (Fla. Stat. § 95.11). Under Florida’s 51% modified comparative fault rule (Fla. Stat. § 768.81), you can recover financial compensation only if you are 50% or less at fault for the incident.
The personal injury claim process follows four distinct legal phases: immediate medical documentation, treatment through Maximum Medical Improvement (MMI), pre-suit demand negotiations, and civil court litigation.
1. The Legal Framework: Florida Personal Injury Laws
Florida’s civil justice system governs personal injury claims through strict statutory deadlines and liability thresholds that directly determine financial recovery.
A. The 2-Year Statute of Limitations (Fla. Stat. § 95.11)
Following the passage of House Bill 837 (HB 837), Florida shortened its statute of limitations for general negligence claims from 4 years to 2 years. Therefore, if your accident occurred after March 24, 2023, you have exactly two years from the date of the incident to file a lawsuit in court. Missing this deadline waives your right to seek damages through the judicial system.
B. Modified Comparative Fault: The 51% Bar Rule (Fla. Stat. § 768.81)
House Bill 837 also shifted Florida from a pure comparative fault system to a modified comparative fault rule with a 51% bar:
- 0% to 50% At Fault: Your financial recovery is reduced by your exact percentage of responsibility.
- 51% or More At Fault: You are legally barred from recovering any financial compensation from the defendant.
C. PIP Insurance & The 14-Day Rule (Fla. Stat. § 627.736)
Florida operates under a no-fault auto insurance framework requiring drivers to carry Personal Injury Protection (PIP):
- The 14-Day Rule: You must receive initial medical treatment within 14 days of a motor vehicle accident. For example, missing this window gives your PIP insurer grounds to deny coverage completely.
- Emergency Medical Condition (EMC): To unlock the full $10,000 in PIP benefits, a licensed physician, osteopath, dentist, or advanced practice registered nurse must certify that you suffered an Emergency Medical Condition. Without an EMC diagnosis, PIP coverage is capped at $2,500.
D. Stepping Outside No-Fault (Fla. Stat. § 627.737)
To pursue a third-party claim or lawsuit against the at-fault driver for non-economic damages (pain and suffering), your injuries must cross the legal threshold by resulting in:
- Significant and permanent loss of an important bodily function.
- Permanent injury within a reasonable degree of medical probability.
- Significant and permanent scarring or disfigurement.
- Death.
2. Step-by-Step Claim Timeline
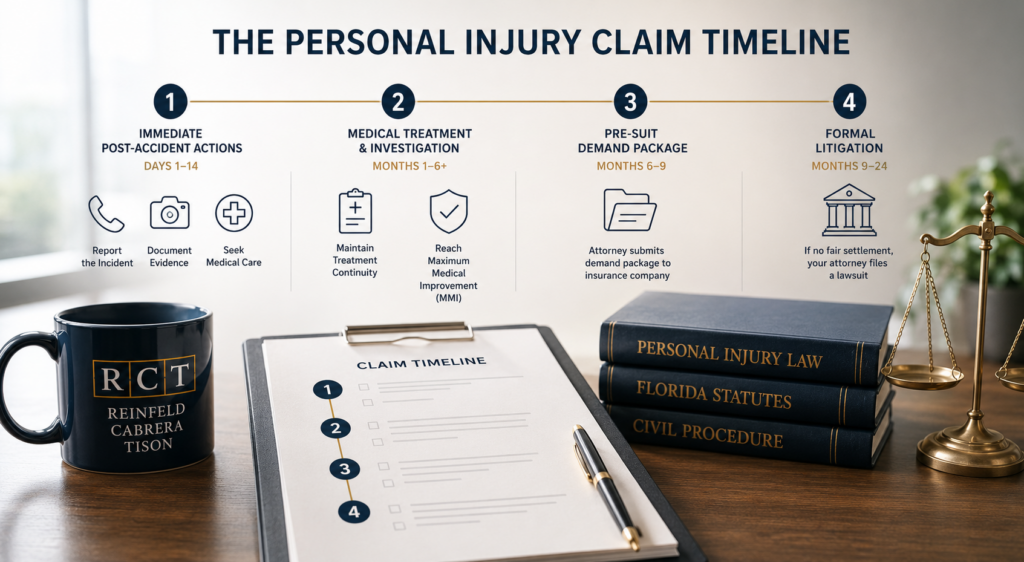
Phase 1: Immediate Post-Accident Actions (Days 1–14)
- Report the Incident: Call 911 immediately. In motor vehicle crashes, ensure law enforcement generates an official Florida Traffic Crash Report.
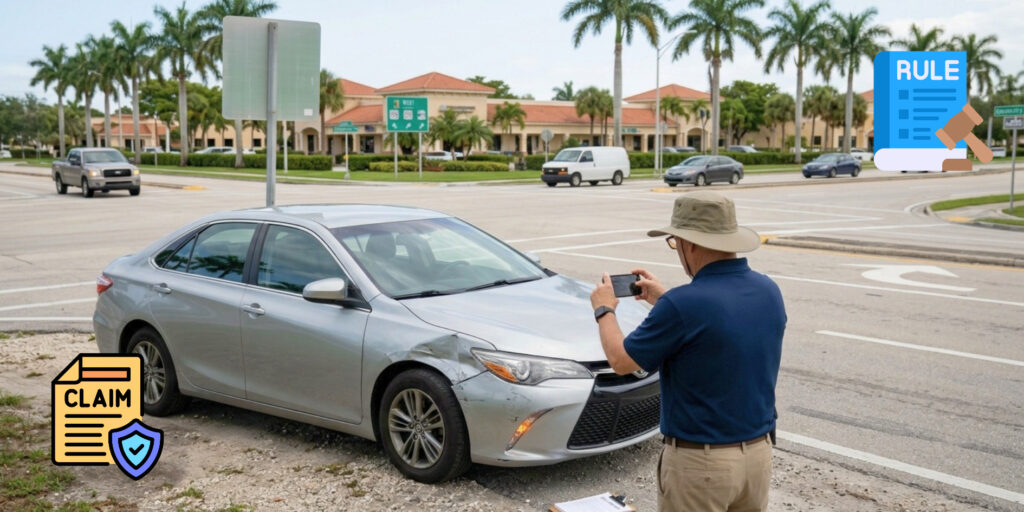
- Document Evidence: Capture photos and videos of vehicle damage, road conditions, hazardous obstacles, and visible injuries. Collect contact information from eyewitnesses.
- Seek Immediate Medical Care: Visit an emergency room or urgent care facility within 14 days to preserve PIP coverage and establish proof of causation.
What Evidence Should You Preserve Before Filing a Florida Personal Injury Claim?
The strength of a Florida personal injury claim often depends on evidence collected during the days and weeks immediately following an accident. Medical records establish the nature of an injury, but other documentation helps explain how the incident happened and who may be legally responsible.
An attorney investigating an accident may need to obtain several types of evidence:
1. Accident reports and incident records
Request the available Florida Traffic Crash Report or incident report. These records can identify the parties involved and document information gathered by responding officers. They are useful starting points, although an officer’s initial findings do not necessarily establish final legal liability.
2. Photographs and video recordings
Preserve photographs of vehicle damage, road conditions, traffic signals, hazardous property conditions, and visible injuries. Surveillance footage from nearby businesses or residential properties may also capture the incident. Because some recording systems automatically overwrite footage, an attorney may need to send a formal preservation request before the material disappears.
3. Medical records and treatment documentation
Keep copies of emergency room records, diagnostic imaging, physician evaluations, prescriptions, and physical therapy reports. These documents help establish the connection between the accident and the injuries being claimed.
4. Witness information
Obtain the names and contact information of people who saw the accident. Independent witnesses may provide important details about vehicle movements, property conditions, or events immediately preceding the incident.
5. Financial documentation
Retain pay stubs, employer statements, invoices, and other records showing accident-related financial losses. If an injury affects your ability to perform your usual occupation, documentation of those limitations may become important when calculating lost earning capacity.
An attorney will identify missing evidence and determine which records need to be obtained from third parties. This is particularly important when surveillance footage, electronic vehicle data, or business records are controlled by someone who has no obligation to preserve them indefinitely.
Step 2: Medical Treatment & Investigation (Months 1–6+)
- Maintain Treatment Continuity: Attend all physical therapy sessions and medical follow-ups. Unexplained gaps in treatment allow insurance adjusters to argue that injuries were pre-existing or minor.
- Reach Maximum Medical Improvement (MMI): MMI occurs when your treating physician states your condition has stabilized and further treatment will not yield major recovery. Reaching MMI allows accurate calculation of future medical costs and lost earning capacity.
What Compensation Can You Recover in a Florida Personal Injury Claim?
A Florida personal injury claim may seek compensation for economic losses and qualifying non-economic damages resulting from an accident. The value of a claim depends on the available evidence, the nature of the injuries, applicable insurance coverage, and the legal rules governing the particular incident.
Economic Damages
Economic damages represent measurable financial losses associated with an injury. Depending on the circumstances, they may include:
- Medical expenses: Emergency treatment, hospitalization, surgery, rehabilitation, prescription medication, and other reasonable medical costs.
- Future medical expenses: Anticipated treatment, additional procedures, or long-term care supported by appropriate medical evidence.
- Lost wages: Income missed while recovering from an accident-related injury.
- Lost earning capacity: Reduced ability to earn income when an injury affects someone’s ability to return to their previous occupation or work at the same level.
- Other financial losses: Additional documented expenses directly attributable to the accident.
Non-Economic Damages
Non-economic damages address losses that do not have a straightforward dollar value and can be continued through and indefinite time period. Depending on the applicable legal requirements, a claimant may seek compensation for:
- Physical pain and suffering.
- Mental anguish and emotional distress.
- Permanent physical impairment.
- Scarring or disfigurement.
- Loss of enjoyment of life.
In Florida automobile accident cases, section 627.737 establishes a threshold that generally must be met before an injured person can recover non-economic damages from an at-fault party. The applicable requirements include permanent injury within a reasonable degree of medical probability, significant and permanent loss of an important bodily function, significant and permanent scarring or disfigurement, or death.
How Does Comparative Fault Affect Compensation?
Florida’s modified comparative fault rule can reduce or eliminate an injured person’s recovery depending on their share of responsibility.
Under section 768.81, a claimant who is 50% or less responsible may recover damages reduced by their percentage of fault. A claimant found more than 50% responsible generally cannot recover damages in a negligence action, subject to statutory exceptions.
For example, if a claim has $100,000 in established damages and the injured person is found 20% responsible, the recoverable amount would be reduced to $80,000.
Calculating damages requires careful examination of medical documentation and evidence concerning the accident. An initial insurance offer may not account for future treatment or the long-term financial consequences of an injury.
Finalization Process 3: The Pre-Suit Demand Package (Months 6–9)
Once medical treatment stabilizes, your attorney submits a formal settlement demand package to the insurance carrier containing:
- Official police reports and witness statements.
- Itemized medical bills, treatment records, and EMC documentation.
- Proof of lost wages verified by your employer.
- Expert medical or economic reports.
Insurance carriers typically have 30 days to review, accept, reject, or counter the demand.
Phase 4: Formal Litigation (Months 9–24)
If the insurer refuses a fair settlement, your attorney files a civil court complaint:
- Pleadings: The complaint is served on the defendant, who has 20 days to file an answer.
- Discovery: Both parties exchange evidence, written interrogatories, and take depositions of witnesses and experts under oath.
- Court-Ordered Mediation: Florida courts require mediation before trial, where a neutral third-party mediator assists both sides in attempting a voluntary settlement.
- Trial: If mediation fails, the case proceeds to jury selection, evidence presentation, arguments, and a final verdict.
3. Why Legal Representation Matters in Florida Claims
Trying to transit Florida’s legal system without counsel exposes personal injury victims to significant procedural risks. Insurance carriers employ dedicated adjusters and legal teams trained to minimize payouts or apply the 51% fault rule to deny claims entirely.
What the Florida Judiciary Says
Florida appellate courts hold self-represented litigants to strict procedural standards:
“A litigant who chooses to represent himself in a complex civil matter is not entitled to special concessions or procedural leniency due to a lack of formal legal training. Unrepresented parties are held to the exact same statutory rules, evidentiary standards, and local procedures as trained attorneys.”
— Florida District Courts of Appeal (confirming doctrine from cases such as Moon v. Newsome, 532 So. 2d 1282).
Case precedents like McCarty v. Estate of Techner (Fla. 5th DCA 1998) show that failing to present qualified medical expert testimony can lead to an immediate dismissal of your case via summary judgment.
4. Local Guidance for South Florida Claims
Claims filed in Broward, Miami-Dade, or Palm Beach counties must abide by specific local court rules across the 17th, 11th, and 15th Judicial Circuits. Critical evidence; such as surveillance footage from private businesses or records from agencies like the Coral Springs or Fort Lauderdale Police Departments, is often overwritten within 30 days.
At Reinfeld Cabrera Tison, our practice is built specifically around South Florida’s judicial landscape. By pairing deep familiarity with local court procedures and judges with a rigorous approach to state statutory deadlines, our team ensures claims are thoroughly built, protected against insurance pushback, and positioned for full financial recovery.